Regular monthly repayments
Simple and predictable, suiting dairy and mixed operations with steady income through the year.

Harvest doesn't wait for the bank. Finance tractors, headers, sprayers and seeders on terms that respect how farm income actually arrives.
On a farm, timing is everything. A tractor breaks down two days before sowing, a header's engine fails with the crop ready to come off, or a sprayer needs replacing in the narrow window when conditions are right. Miss that window and the cost isn't just a repair bill, it's a season's worth of yield. That's why farmers searching for equipment finance by tomorrow aren't being impatient; they're protecting the year.
Agricultural equipment finance lets farmers buy or replace machinery without draining the cash reserves they rely on between harvests. The machine secures the loan, and because farm equipment from well-known makers holds its value, lenders are generally comfortable financing it on reasonable terms, with approval moving fast when the paperwork is in order.
Loanster works with croppers, graziers, dairy farmers, horticulturalists and contractors across Australia. Tell us what you need and when it has to be in the paddock. A real person looks at your situation and works towards apply today, cashed up tomorrow, so the machine arrives when the season does, not a fortnight after it.
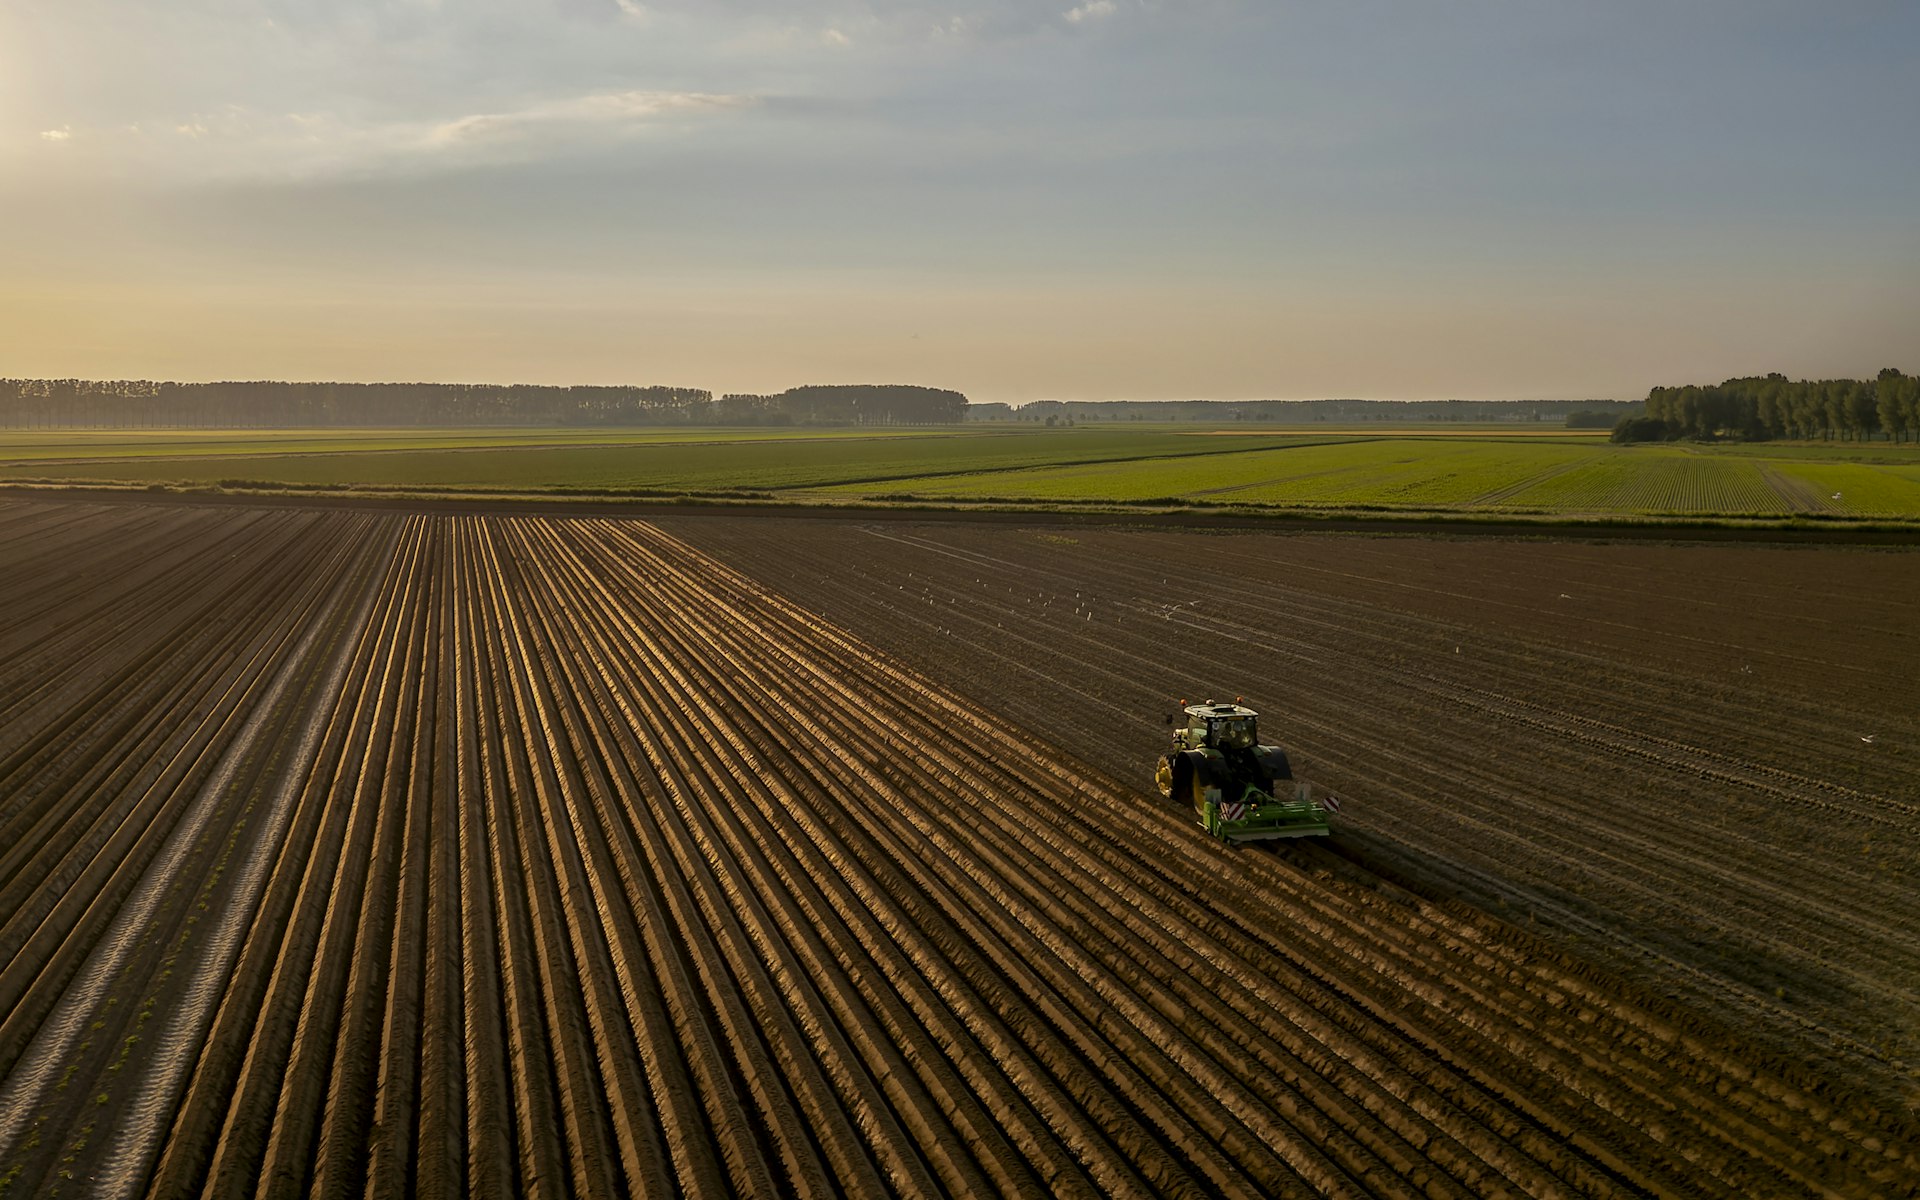
Farm income is seasonal, and finance can often be shaped to suit.
Simple and predictable, suiting dairy and mixed operations with steady income through the year.
Some lenders allow larger repayments after harvest and smaller ones in lean months, matched to when money comes in.
A lump sum left at the end lowers regular repayments, useful if you plan to trade the machine in on a newer model.
Most machinery and equipment used to run a farm can be financed. Lenders are happiest with established brands that have strong resale markets, but they also fund specialist gear for horticulture, viticulture and livestock operations.
Farm vehicles such as utes and light trucks can often be included too. For broader farm funding, such as land improvements, stock or working capital, see our page on farm business loans.
Call the dealer first and lock in a replacement with a written quote or tax invoice. Ask whether they can deliver once finance settles, and whether a loan machine is available in the meantime. Then send that invoice, your ID and recent bank statements together.
On a straightforward application, approval can happen quickly and next-business-day settlement is possible. If the replacement is a private sale or an older machine, allow a little longer for the lender's checks. Our urgent equipment finance page has more on emergency purchases.
Yes. A lot of farm machinery changes hands through clearing sales, dealers and neighbours. Lenders will want the make, model, year, hours and serial number, plus proof of ownership for private sales.
Clearing sales move fast, so get pre-approval before sale day. That way you can bid with confidence knowing the money is lined up. More detail is on our used equipment finance page.
Start the 60-second enquiry now. When your documents are ready and the deal is straightforward, being cashed up as soon as tomorrow is possible for eligible applicants.

Lenders understand that farm income goes up and down with seasons, prices and weather. They'll usually look at bank statements across a longer period, recent financial statements, and the farm's overall position rather than one bad year.
If you've had a tough season, explain it. A lender who understands that a drought year affected income can look at the stronger years around it. Drought, flood or fire recovery isn't an automatic barrier to finance. Having your accountant's latest figures and a short note on the outlook for the coming season ready can make the assessment smoother and faster.
If you own land, a property-secured business loan can sometimes be faster or more flexible than equipment finance, especially for older machines or several items at once. Property-secured business loans range from $20,000 to $5,000,000 by first mortgage, second mortgage or caveat.
Rural property can be more complex to value than city property, so discuss this option early. Our page on secured business loans explains how property security works.
Most farm machinery attracts GST, and many lenders will finance the GST-inclusive price. How you claim it back, and how the machine is depreciated, depends on your circumstances and the finance structure you choose.
Rules around depreciation and write-offs change, so talk to your accountant before you sign. They can help you choose between a chattel mortgage, lease or hire purchase from a tax point of view.
Our enquiry takes about 60 seconds. There's no credit check when you first enquire and we don't send your details to a crowd of lenders. A real person who understands seasonal business looks at what you need.
Fill in the form accurately so we can match you first time. Start your 60-second enquiry and let's get that machine working before the window closes.
Loanster keeps the enquiry process straightforward: no credit check to enquire, a real person looks at your situation, and your details are not sprayed out to a pile of lenders.
Personal details are submitted through a secure form and are not sent through URL query strings.
Enquiries can include ABN, BAS, ATO, bank statement and asset details where relevant.
Approval, pricing, loan amounts and funding times depend on lender assessment.
Loanster helps identify what information may be needed before a lender can make a decision.
Some lenders offer seasonal or structured repayments that match harvest or sale income. Ask about it when you enquire so we can find a lender that offers it.
Yes. Get pre-approval before sale day so the lender only needs the final invoice to settle quickly after you buy.
Not always. Established farm businesses buying from a dealer can often finance the full price, while older machines or private sales may need a deposit or trade-in.
Yes. Contract harvesters finance headers and fronts regularly, and lenders will look at your contracts and history alongside the machine.
Not necessarily. Lenders look at the broader picture across several years, and a clear explanation of a tough season helps.
Yes. Refinancing owned machinery can release cash for inputs, stock or another purchase. See our equipment refinance page for details.
Inputs to buy before sowing, a header that broke mid-harvest or stock to restock after a tough year. Farm finance that respects how the land pays.
Busy summers, dead winters, a Christmas rush that needs stock in October. Seasonal finance smooths out the year so the quiet months do not sink you.
Whether it's a CNC router, a packaging line or a workshop full of gear, machinery finance spreads the cost so your cash stays in the business.
Your yard is full of machines and vehicles that are paid off. Turn some of that value into working capital, fast, without selling a thing.
See every equipment loan page on Loanster in one place.
Tell Loanster what kind of finance you are looking for and the team will guide you through the next step. Please fill in the form accurately so we can match you first time. Finance is subject to lender approval, eligibility criteria, terms and conditions.
Prefer to talk? Call 03 9999 7370.
Last reviewed: 24 October 2026
Pick one to start. A real person reviews every enquiry.