Dry or wet hire
Best for short jobs or machines you'll rarely use. No commitment, but hire costs add up fast on longer contracts.

Won the tender, now you need the machine on site Monday. Construction equipment finance gets excavators, loaders and plant paid for fast.
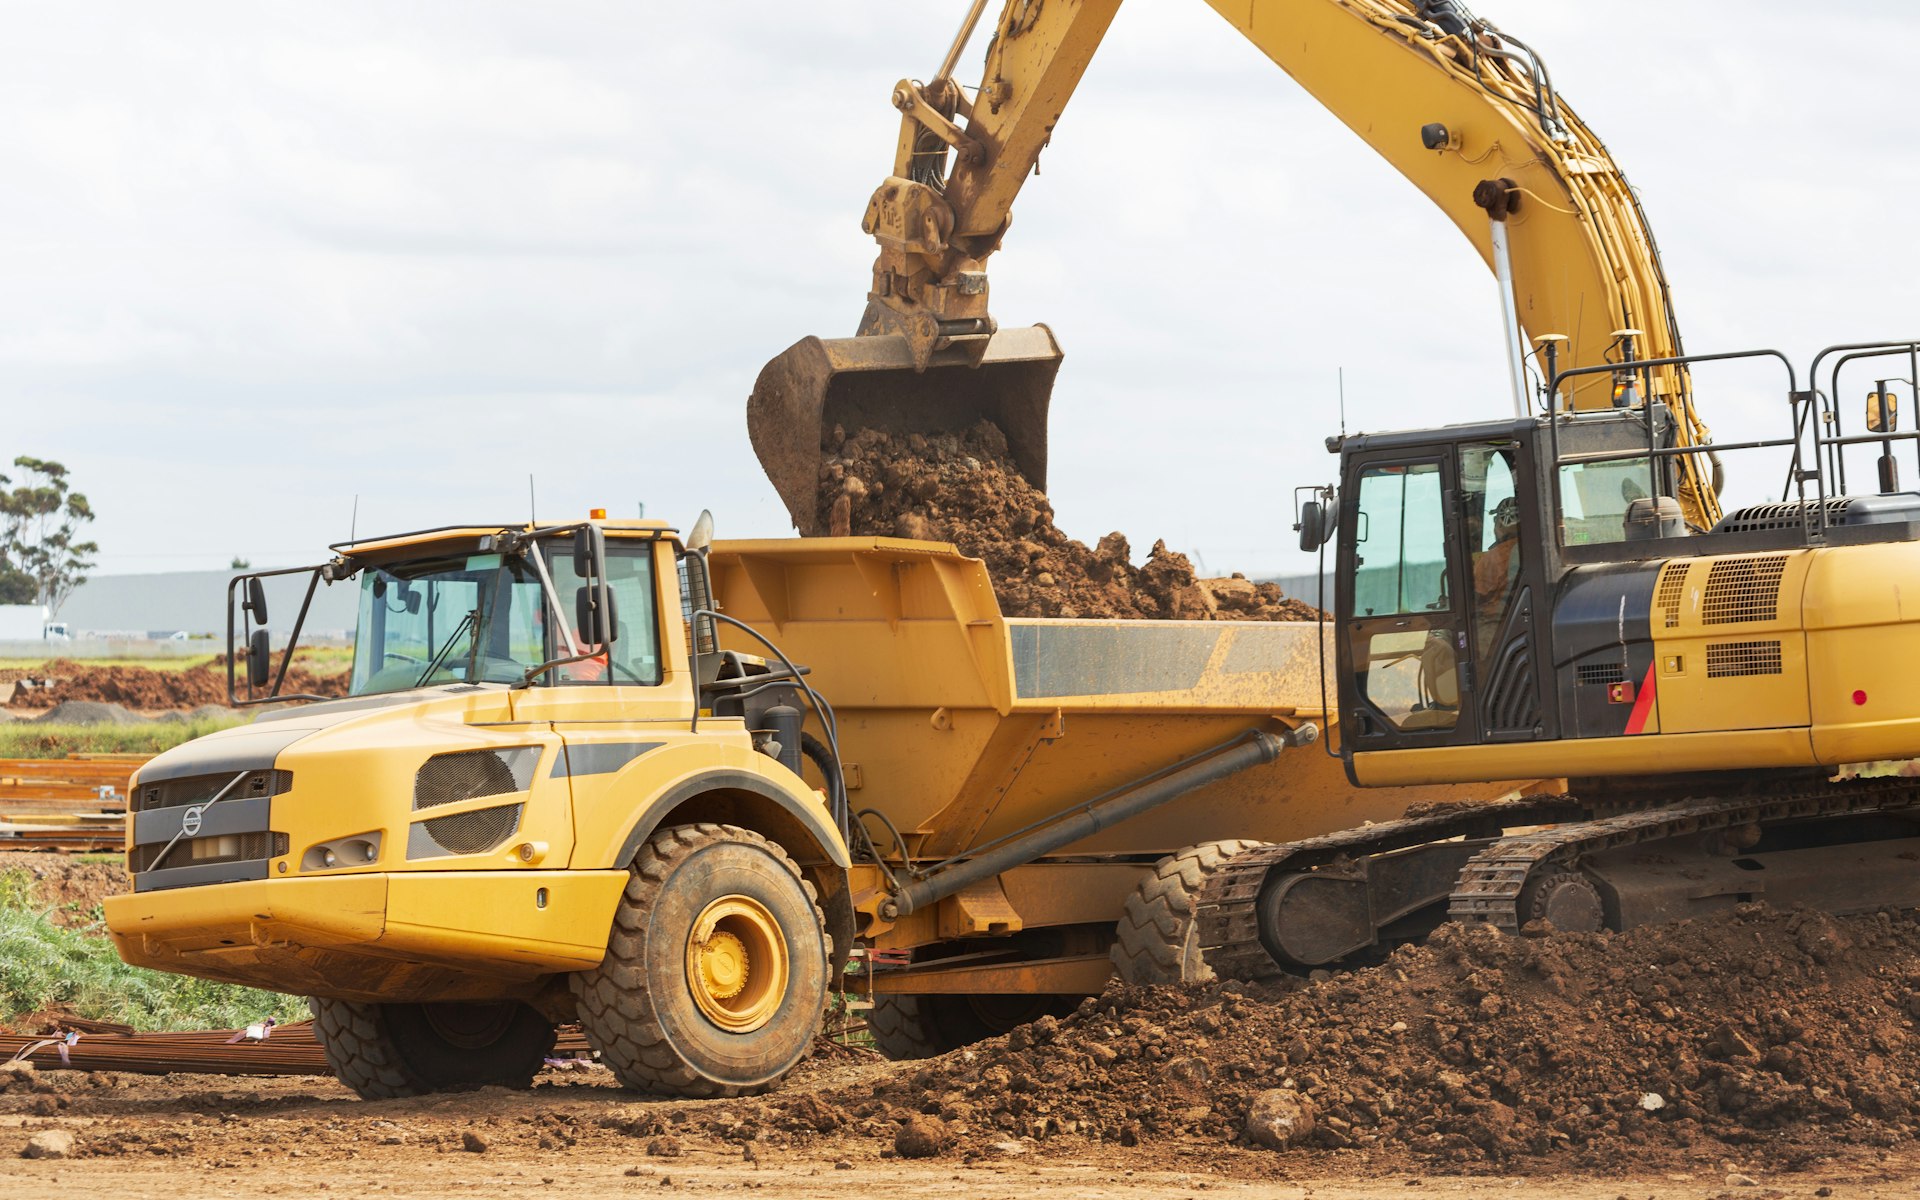
Construction runs on deadlines. A head contractor confirms your package on Thursday afternoon and wants a second excavator working by Monday. A skid steer throws a track on a slab pour. A civil job needs a roller you don't own and the hire rate makes buying the obvious answer. In each case, the work is there and the only thing missing is the machine.
Construction equipment finance is designed for exactly this. The machine is the security, so lenders can move quickly when they understand the asset, the supplier and your business. Earthmoving plant from established brands is among the easiest gear to finance because it holds its value and has a deep resale market. That gives lenders confidence, and confidence is what turns a week-long assessment into a quick one.
Loanster helps builders, earthmovers, civil contractors and specialist trades get that finance moving. Tell us what you need and the date it has to be working. A real person looks at your situation and works towards apply today, cashed up tomorrow, so the machine turns up when the job does.
Each option has a place, depending on how long you need the machine.
Best for short jobs or machines you'll rarely use. No commitment, but hire costs add up fast on longer contracts.
Suits machines you'll use across many jobs. Repayments are fixed and the asset builds equity in your business.
Release cash from machines you already own to fund a deposit, wages or materials on a big new contract.
Just about anything that works on a site. Lenders are most comfortable with recognised brands and models that have a strong second-hand market, but specialised gear is often possible with a little more detail.
Attachments such as buckets, augers, rock breakers and tilt hitches can usually be added to the same contract as the machine. For the trucks that move your gear between sites, see truck finance and trailer finance.
When everything lines up, quickly. A dealer tax invoice with serial numbers, director ID, and recent business bank statements is the core of a fast file. On a straightforward application, approval can happen quickly and next-business-day settlement is possible.
What slows construction deals down is usually paperwork. An invoice in the wrong entity's name, a private seller who can't show the machine is unencumbered, or a recent restructure can all add days. Get the invoice right and start the 60-second enquiry as soon as you have it.
Yes, and it's common in earthmoving. The catch is timing: auction houses expect payment within days, so get pre-approval before you bid. That way the lender already knows your business and only needs the final invoice to settle.
Older auction machines may face shorter terms or need a deposit. Our used equipment finance page explains what lenders look for in second-hand gear.
Start the 60-second enquiry now. When your documents are ready and the deal is straightforward, being cashed up as soon as tomorrow is possible for eligible applicants.

Construction cash flow is lumpy. You might be paying wages, materials and machine repayments for weeks before the first progress claim is paid. Financing the machine keeps your cash free for those costs rather than tying it up in plant.
If the gap is bigger than the machine, consider separate working capital. A construction business loan or business line of credit can carry you between claims, sized on your turnover and bank statements.
Possibly. Earthmoving gear is strong security, which gives lenders room to look at the whole picture rather than just a credit score. Recent defaults, ATO debt or a past business failure will be considered case by case.
The key is honesty at the start. Tell us what happened and what's changed, and we can approach the right lender rather than wasting time on one that will say no.
New machines come with warranty, the latest emissions and safety features, and usually the smoothest finance approval. Used machines cost less upfront and can be just as productive, but may need inspections and attract shorter terms.
The right answer depends on how many hours you'll put on it, how long you plan to keep it, and how much downtime you can tolerate. Your accountant can help with the tax side of either choice. A useful rule of thumb: if the machine will be the backbone of your work for years, new often pays off; if it's a second unit for peak periods, a well-maintained used one may be the smarter buy.
The enquiry takes about 60 seconds, with no credit check at that point and no spraying your details across a long list of lenders. A real person reads it and comes back to you with a practical plan.
Accurate details help us match you first time. Subject to lender approval, your machine could be paid for as soon as tomorrow and working on site by Monday.
Loanster keeps the enquiry process straightforward: no credit check to enquire, a real person looks at your situation, and your details are not sprayed out to a pile of lenders.
Personal details are submitted through a secure form and are not sent through URL query strings.
Enquiries can include ABN, BAS, ATO, bank statement and asset details where relevant.
Approval, pricing, loan amounts and funding times depend on lender assessment.
Loanster helps identify what information may be needed before a lender can make a decision.
Established businesses buying common machines from a dealer can often finance the full price. Newer businesses, older machines or private sales may need a deposit.
Yes, attachments can be financed on their own or added to the machine's contract. Bundling them is usually simpler.
Not always, but a signed contract or letter of award can strengthen an application, particularly for newer businesses or larger machines.
Sometimes. Some hire companies sell ex-fleet machines, and those purchases can be financed like any other used asset.
Terms vary by lender, machine type and age. Lenders typically limit how old a machine can be by the end of the contract.
Yes. Sole traders with an ABN and steady trading history regularly finance mini excavators and similar gear for their own work.
Progress claims paid late, wages due Thursday and a machine needed on site Monday. Construction finance that keeps the project moving on schedule.
Whether it's a CNC router, a packaging line or a workshop full of gear, machinery finance spreads the cost so your cash stays in the business.
A truck off the road is income off the books. Get a replacement or extra unit financed quickly, whether it's a prime mover, rigid or tipper.
Materials to buy, an apprentice to pay and a client who is thirty days late. Tradie finance built around how trade businesses actually get paid.
See every equipment loan page on Loanster in one place.
Tell Loanster what kind of finance you are looking for and the team will guide you through the next step. Please fill in the form accurately so we can match you first time. Finance is subject to lender approval, eligibility criteria, terms and conditions.
Prefer to talk? Call 03 9999 7370.
Last reviewed: 24 October 2026
Pick one to start. A real person reviews every enquiry.