Buy with a chattel mortgage
You own the forklift from day one, with the lender holding security over it. Suits machines you plan to run for years.

When the forklift stops, so does everything else. Fund a replacement or an extra unit quickly and keep your cash for the rest of the business.
In most warehouses and yards, the forklift is the machine nobody thinks about until it stops. Then the trucks back up at the dock, staff stand around waiting, and stock that should be shipping sits on the floor. A single breakdown can cost far more than a repayment.
Forklift finance lets you buy or lease a replacement, or add a second unit for busy periods, without pulling a large sum out of working capital. The forklift itself secures the loan, which makes it a well-understood asset for lenders.
Whether you run a timber yard, a cold store, a brewery or a distribution centre, the approach is similar: choose the right machine, line up the paperwork, and get it delivered before the backlog grows.
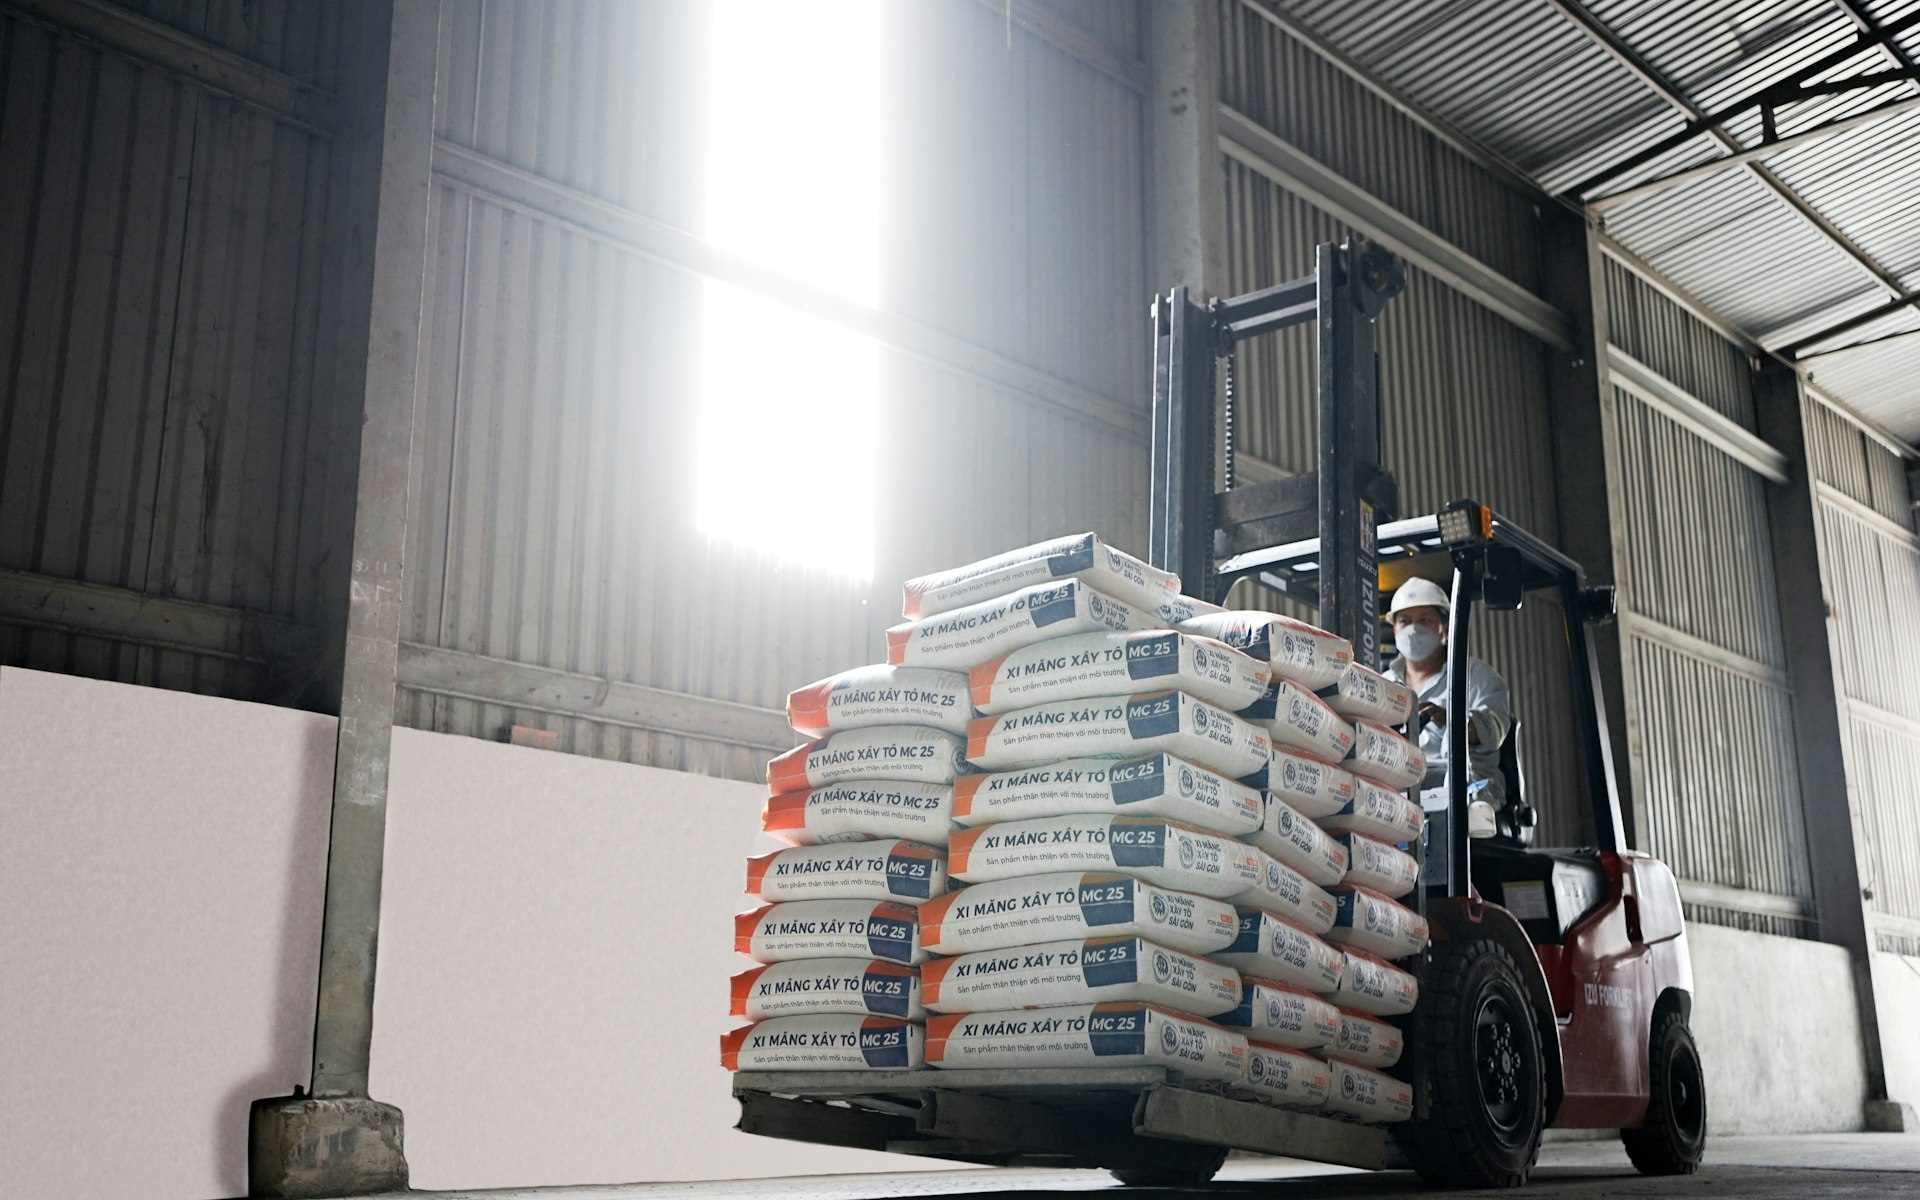
The right structure depends on how hard the machine will work and how long you plan to keep it.
You own the forklift from day one, with the lender holding security over it. Suits machines you plan to run for years.
The lender owns it and you lease it for a fixed term with a residual. Useful if you rotate fleet on a regular cycle.
You pay to use the forklift, sometimes with servicing included, and hand it back at the end. Handy for seasonal peaks.
Most materials-handling equipment with a serial number and resale market can be considered, new or used, from a dealer or sometimes from a private seller.
Speed depends mostly on how ready you are. Approval and settlement can move fast when the tax invoice or quote, ID and bank statements are ready, and next-business-day settlement is possible for straightforward applications.
Here is a typical scenario: a food distributor's forklift fails on a Wednesday, two days before a large order goes out. The dealer has a suitable used unit in stock, the owner emails the quote and statements that afternoon, and the replacement is on the dock in time. If you are in a similar spot, see urgent equipment finance for what to do first.
A new forklift brings warranty, the latest safety features and often better battery technology. A used machine can be on the floor faster and costs less upfront, which can matter when the business is under pressure.
Lenders fund both, though older units may face age limits or need an inspection. Check the hours on the meter, service history and battery condition before you commit. Our guide to used equipment finance covers what lenders look for in second-hand gear.
Start the 60-second enquiry now. When your documents are ready and the deal is straightforward, being cashed up as soon as tomorrow is possible for eligible applicants.

If the forklift works every shift and you look after it well, owning it can make sense, because it keeps earning long after the loan is repaid. If you prefer predictable costs and regular upgrades, or only need extra capacity for part of the year, leasing or renting may suit better.
We break down the trade-offs in equipment lease vs loan. For tax and GST treatment of each option, talk to your accountant, as it depends on your structure and how the asset is used.
Yes. Many businesses finance forklifts alongside racking, mezzanines, dock levellers and shelving. Some of these items can be funded as equipment, while others may sit better in a fit-out loan or broader business facility.
If you are taking on a new warehouse or a big contract, a combined approach can save time and simplify repayments. Tell us the full picture when you enquire and we will suggest the cleanest structure.
Winning a new customer is great news until you realise the warehouse cannot physically handle the extra volume. A second or third forklift, more racking and a few casual staff can all be needed in the same fortnight.
Equipment finance can cover the machines, while a working capital facility can carry wages and stock until the new customer starts paying. Trading businesses may be able to access unsecured or line-of-credit options typically from $5,000 to $500,000, sized on turnover and bank statements. Read more about working capital loans and business expansion loans.
Bring the whole plan to us at once and we can stage the funding so nothing holds up the start date.
There is no credit check when you first enquire, a real person looks at your situation, and your details are not passed around to a crowd of lenders. Please complete the form accurately so we can match you first time, subject to lender approval.
Have the dealer's quote handy? Start the 60-second enquiry and let us know how soon the forklift needs to be working.
Loanster keeps the enquiry process straightforward: no credit check to enquire, a real person looks at your situation, and your details are not sprayed out to a pile of lenders.
Personal details are submitted through a secure form and are not sent through URL query strings.
Enquiries can include ABN, BAS, ATO, bank statement and asset details where relevant.
Approval, pricing, loan amounts and funding times depend on lender assessment.
Loanster helps identify what information may be needed before a lender can make a decision.
Many established businesses can finance the full price, subject to lender approval. Newer businesses or those with credit issues may be asked for a deposit or trade-in.
Yes, batteries, chargers and attachments are often included when bought with the forklift. Standalone replacement batteries may also be fundable, depending on the lender.
The lender assesses the business, not the operator. You will still need properly licensed operators to use the forklift on site.
Often, yes. The lender may want proof of ownership, the serial number and confirmation that no finance is owing on the machine.
It can be. Newer businesses may need a deposit or stronger supporting documents, but a forklift is well-understood security for lenders.
Yes. Some owners buy a second unit, while others use a rental for the busy months. We can help you weigh up which suits your cash flow.
Finance eligible equipment for your business while preserving cash flow for wages, suppliers and day-to-day operations.
Whether it's a CNC router, a packaging line or a workshop full of gear, machinery finance spreads the cost so your cash stays in the business.
Upgrade the line, replace a failed machine or take on a bigger order, while your cash stays available for materials and wages.
Shelves to fill, a bulk discount expiring Friday or a peak season around the corner? Stock finance puts the cash in your hands before the sales arrive.
See every equipment loan page on Loanster in one place.
Tell Loanster what kind of finance you are looking for and the team will guide you through the next step. Please fill in the form accurately so we can match you first time. Finance is subject to lender approval, eligibility criteria, terms and conditions.
Prefer to talk? Call 03 9999 7370.
Last reviewed: 24 October 2026
Pick one to start. A real person reviews every enquiry.