Equipment loan
Your business owns the system and repays it over an agreed term. Suits owner-occupiers planning to stay long term.

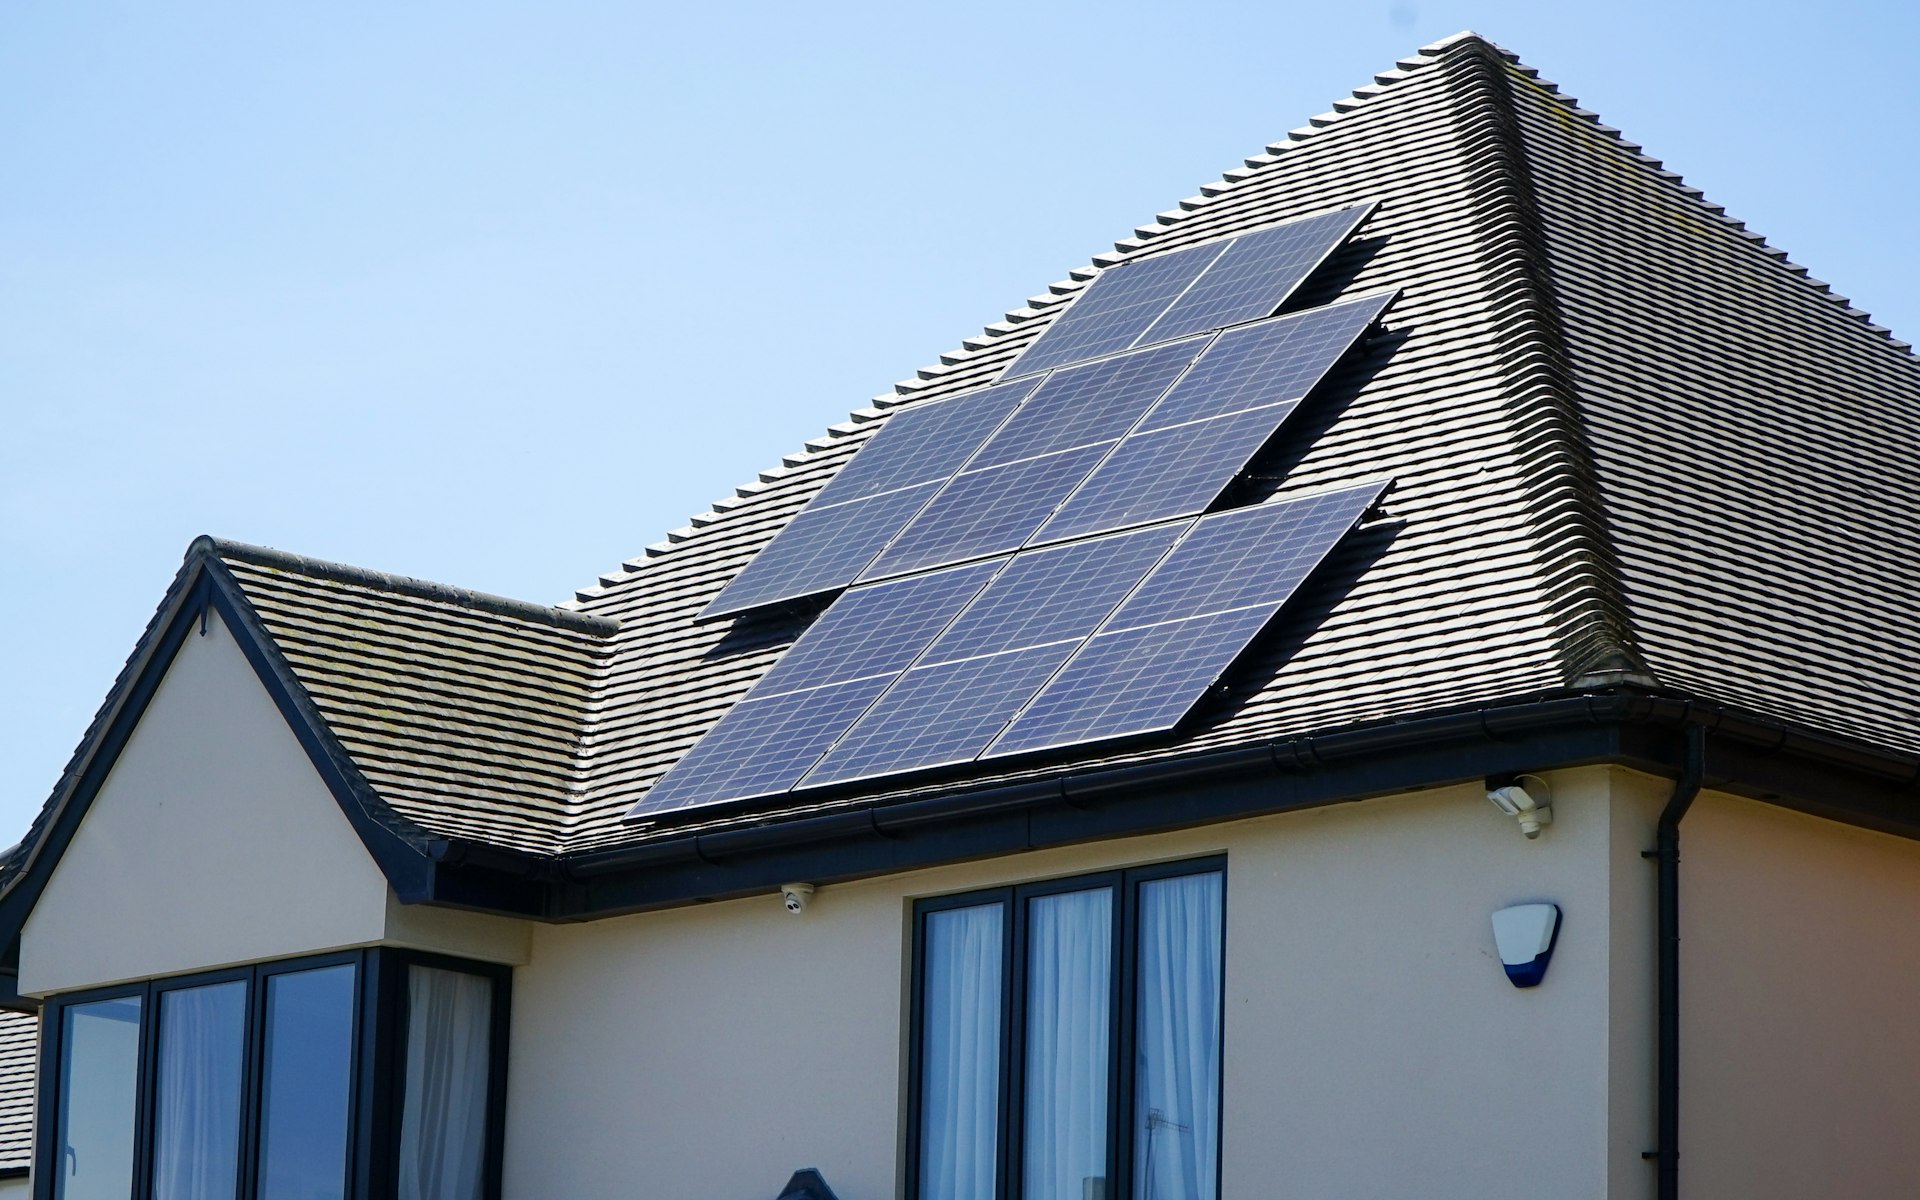
Install solar panels, inverters and batteries on your shed, shop or factory without draining the cash you need to run the business.
Yes. Solar panels, inverters, battery storage and associated electrical work can be financed much like any other business equipment. Instead of paying the full installation cost upfront, you spread it across a term and keep your working capital for stock, staff and growth.
For many businesses the appeal is simple: energy is a big, unavoidable cost, and the repayments on a well-designed system can sit alongside a lower power bill. How much you save depends on your usage, your roof, your tariff and the system itself, so get a proper assessment from your installer.
Farms, cold stores, workshops, cafes, medical clinics and manufacturers all use solar finance. If your premises run during daylight hours, it is worth looking at closely.
The best approach depends on whether you own the building and how you want the asset treated.
Your business owns the system and repays it over an agreed term. Suits owner-occupiers planning to stay long term.
The lender owns the equipment and you pay to use it. May suit businesses that prefer a predictable payment or want the option to upgrade.
If solar is part of a larger project, a loan secured by property from $20,000 to $5,000,000 can cover it alongside other works.
Lenders generally consider the full commercial installation from a reputable, accredited installer, including:
Ask your installer for an itemised quote that separates the panels, inverter, battery and labour. It makes the lender’s job easier and avoids questions that could otherwise slow down approval.
It helps, but it is not always essential. If you rent, you will usually need the landlord's written consent to install, and a lender may want to see your lease terms to make sure you will be there long enough to benefit.
Owner-occupiers often have the most options, including bundling solar into a wider upgrade. If you are also fitting out the premises, our page on fit-out loans may help you plan the whole project.
Solar is rarely an emergency, but timing still matters. Installers book out, quotes expire, and some owners want the system running before summer or before EOFY. Approval and settlement can move fast when the installer's quote, ID and bank statements are ready, and next-business-day settlement is possible for straightforward applications.
Many lenders pay the installer directly, sometimes in stages: a deposit on order and the balance on commissioning. Ask your installer how they like to be paid so we can line up the right lender. Want it moving now? Start the 60-second enquiry.
Start the 60-second enquiry now. When your documents are ready and the deal is straightforward, being cashed up as soon as tomorrow is possible for eligible applicants.

As with most business equipment, a GST-registered business may be able to claim GST on the purchase, and depreciation or other deductions may apply. Government incentives and certificates for solar also exist and change over time, and your installer will usually factor them into the quote.
Treatment depends on your structure and on how you finance the system, so please confirm the details with your accountant before you sign. We do not give tax advice, and you should not rely on a general summary for something this specific.
Sometimes. If you already have equipment finance in place, a lender may be able to add the system as a new asset. If you own other equipment outright, equipment refinance could release cash toward the project.
Trading businesses can also consider an unsecured facility sized on turnover, typically $5,000 to $500,000, though for a dedicated solar purchase an equipment structure is usually cleaner. Agricultural businesses may also want to look at agricultural equipment finance for pumps and other on-farm gear.
Lenders want to know the business is trading steadily and can comfortably meet repayments, so recent business bank statements carry a lot of weight. They will also look at the installer, the components and the quote, because a clear, itemised quote from an accredited installer is far easier to approve than a vague one.
If you are a newer business or your tax returns are behind, solar can still be possible. Our page on low doc equipment finance explains how lenders assess applicants without full financials, and the equipment finance checklist lists everything worth gathering before you enquire.
Credit issues are considered case by case, so mention anything relevant up front.
Send through the basics: the installer's quote, your business details and roughly when you want the job done. There is no credit check at this stage and a real person looks at every enquiry.
Please fill in the form accurately so we can match you first time. All finance is subject to lender approval, and we only send your details where they genuinely fit.
Loanster keeps the enquiry process straightforward: no credit check to enquire, a real person looks at your situation, and your details are not sprayed out to a pile of lenders.
Personal details are submitted through a secure form and are not sent through URL query strings.
Enquiries can include ABN, BAS, ATO, bank statement and asset details where relevant.
Approval, pricing, loan amounts and funding times depend on lender assessment.
Loanster helps identify what information may be needed before a lender can make a decision.
Many businesses finance the full installation, subject to lender approval. Some may be asked for a deposit depending on credit history and time in business.
Often, yes. Batteries added to an existing system can usually be funded as equipment if they come from an accredited installer.
It depends on your usage, tariff, system size and finance terms. Ask your installer for a realistic estimate based on your actual bills rather than relying on general claims.
Usually, with your landlord's written consent and enough time left on your lease. A lender may ask to see the lease.
Interest, depreciation or lease payments may be deductible for a business, but it depends on your circumstances. Confirm with your accountant.
Yes, many lenders will fund solar alongside pumps and related gear in one deal, which keeps things simple.
Finance eligible equipment for your business while preserving cash flow for wages, suppliers and day-to-day operations.
Harvest doesn't wait for the bank. Finance tractors, headers, sprayers and seeders on terms that respect how farm income actually arrives.
A bigger contract, a second site or a new crew. Growth rarely waits for your bank account to catch up, so here is how to fund it quickly.
Own it, lease it or rent it? The answer shapes your cash flow, your balance sheet and what happens when the gear gets old.
See every equipment loan page on Loanster in one place.
Tell Loanster what kind of finance you are looking for and the team will guide you through the next step. Please fill in the form accurately so we can match you first time. Finance is subject to lender approval, eligibility criteria, terms and conditions.
Prefer to talk? Call 03 9999 7370.
Last reviewed: 24 October 2026
Pick one to start. A real person reviews every enquiry.